
The Exempt Test and What Happens When a Contract Fails It
The exempt test does not let a person put unlimited money into a life insurance contract tax sheltered. It caps how much accumulating fund a contract may carry relative to its death benefit, and a contract that exceeds the cap at a policy anniversary, without the insurer adjusting it in time, stops being an exempt policy. Section 306 of the Income Tax Regulations sets the test. Once a contract is not exempt, section 12.2 of the Income Tax Act includes its annual growth in income, and this page found no route back.
The exempt test is the rule that decides whether a life insurance contract is taxed as insurance or taxed like an account. This page covers the mechanism of that test in section 306 of the Income Tax Regulations, the annual reading, the anti dump-in rule, the insurer's contractual tools for staying inside the line, and what follows under section 12.2 of the Income Tax Act when a contract crosses it. It does not repeat the plain definition, which is on the glossary page, and it does not restate why growth inside an exempt contract is deferred rather than taxed each year, which is on the tax deferred growth page.
Everything below is general information written by a licensed insurance professional. The test is applied by the issuing insurer to the actual contract, using assumptions the Regulations prescribe, and no page can tell a reader where a particular contract sits against it. Canadian Wealth Creation Centre Inc., trading as IBC Financial, is not authorized to give legal, tax or notarial advice and gives none here. What a failure would cost a particular owner is a question for a Chartered Professional Accountant with the insurer's figures in hand.
What does the exempt test measure?
It measures how much money is accumulating inside a life insurance contract relative to the death benefit it provides. A modest fund against a large death benefit is insurance in the eyes of the Income Tax Act. A large fund against a small death benefit looks like savings in an insurance form, and the test is the line between them.
The comparison is written in paragraph 306(1)(a) of the Income Tax Regulations. At a policy anniversary, the accumulating fund of the actual contract, determined without regard to any policy loan, must not exceed the total of the accumulating funds of the exemption test policies issued in respect of it. Those exemption test policies are not real contracts. They are notional contracts the Regulations deem to exist beside the real one, with terms fixed by subsections 306(3) and 306(4), and their only purpose is to set a ceiling.
The section then adds three conditions that make the ceiling a permanent feature rather than a one-day check. Paragraph 306(1)(b) requires that, assuming the terms of the contract do not change and making reasonable assumptions about everything else, it be reasonable to expect the ceiling to be respected at every future policy anniversary before the exemption test policies reach their endowment date. Paragraph 306(1)(c) requires the ceiling to have been respected at every past anniversary. Paragraph 306(1)(d) requires the forward-looking condition to have been met at all times since the first anniversary.
Read together, those four paragraphs describe a contract that has never been over the line, is not over the line today, and is not expected to cross it. Subsection 306(2) fills in the first year: a contract that is exempt at its first policy anniversary is deemed to have been exempt from the date of issue. That is the whole of what exempt means. It is a description of a contract's proportions, not a label an insurer attaches or a status an owner applies for.
What is the accumulating fund, and where does it come from?
the number that decides what is taxable
The adjusted cost basis
- 01The tax cost of the contract to its owner
- 02It rises with the premiums that are paid
- 03It falls as the net cost of pure insurance is deducted
- 04It decides how much of an amount taken out is taxable
- 05On a long held contract it declines toward nothing
The accumulating fund is the tax measure of what is inside a contract, and it is defined by section 307 of the Income Tax Regulations rather than by the contract itself. It is not the cash surrender value on a statement, and it is not the total premiums paid. It is a reserve figure computed under rules the Regulations prescribe.
For an interest in a life insurance policy that is not an exemption test policy, section 307 sets the accumulating fund by reference to the amount the life insurer determines under the reserve rules the Regulations point to, scaled to the taxpayer's share of the contract. For an exemption test policy, the section prescribes a separate computation, with its own treatment of the premium paying period and, once that period has ended, the present value of the future benefit on death. Subsection 307(2) fixes the interest and mortality assumptions the notional contracts are computed on, and the Regulations set a floor under the interest rate that may be used.
That is why an owner cannot run the test from a statement. The number on the real side comes from the insurer's reserve calculation, and the number on the notional side comes from a contract that exists only in the Regulations, computed on assumptions the owner never sees. The insurer performs the comparison at each anniversary, and an owner who wants to know the result asks for it in writing.
Two features of the notional side matter for what follows. The exemption test policies are deemed to have a level benefit on death for their whole term, and a benefit that is payable at the earlier of the death of the person insured and an endowment date the Regulations set. Both features fix the size of the ceiling, and both are outside anyone's control, which is the point of writing them into a Regulation rather than into a contract.
When is the test applied, and what is the 250 percent rule?
The test is read at every policy anniversary, and a second and sharper test is read at the tenth anniversary and each one after it. The first compares the real fund against the notional ceiling. The second, in subsections 306(6) and 306(7) of the Income Tax Regulations, looks back three years and asks whether the fund has grown too fast.
The mechanism of the second test is simple to state. At the tenth or a later policy anniversary, if the accumulating fund of the contract, again without regard to any policy loan, exceeds 250 percent of the accumulating fund on its third preceding policy anniversary, subsection 306(7) applies. For a contract issued after 2016, the Regulations add further conditions before the subsection applies, including a comparison of the fund against a fraction of the total accumulating funds of the exemption test policies. Where it does apply, each exemption test policy is deemed to have been issued on the later of the third preceding anniversary and its original deemed date, and at no other time.
The consequence of that re-dating is that the notional contracts start again from a later point, so the ceiling they set is lower than the one the real contract had been measured against. The rule exists to catch a large deposit made late in the life of a contract that had been funded modestly until then, which is why it is called an anti dump-in rule. It does not care why the money arrived. A deposit made in good faith and a deposit made to shelter a windfall are read identically.
The reading is also reset by the ordinary mechanics of subsection 306(3). Each time the benefit on death at a policy anniversary exceeds 108 percent of the benefit on death at the later of the date of issue and the preceding anniversary, a new exemption test policy is deemed to have been issued. For a contract issued after 2016 that reading is done coverage by coverage rather than for the contract as a whole. An owner adding paid-up additions each year, which is the way a participating contract is usually funded toward the line, is moving both sides of the comparison at once, and how that works is on the paid-up additions page.
What are the honest limits of funding a contract to the line?
what a rider actually buys
The paid-up additions rider
- A small block of fully paid whole life coverage
- Bought with a declared dividend or an extra deposit
- It needs no further premium once it is purchased
- It adds to both cash value and death benefit
- The rider carries a maximum set by the exempt test
A contract funded to the maximum the test permits lives near the line by design, and the person who benefits most from the test is the person most likely to trip it. Those two facts belong together, and a page that states the first without the second has left out the part the reader needs.
The strategy is the Canadian application of the approach known as The Infinite Banking Concept®, originated by R. Nelson Nash; the mark belongs to Infinite Banking Concepts, LLC, with which this practice has no affiliation. The strategy funds a participating whole life contract heavily in its early years, usually with paid-up additions, precisely because the deferral inside an exempt contract is worth having. That funding pushes the accumulating fund up faster than a contract paid at its base premium, and the closer the fund sits to the notional ceiling, the less room there is for anything unexpected. Insurance is insurance, it is not an investment, and the deferral is a characteristic of a contract that stays exempt rather than a promise attached to the strategy.
Several ordinary events narrow the room. A dividend scale that comes in above the one the insurer assumed adds more paid-up additions than expected, and dividends are not guaranteed in either direction. A premium refund the owner declines to accept, a change to the payment pattern, or a large deposit after a quiet period each move the real fund toward the ceiling or trigger the 250 percent reading. A reduction of the death benefit, which subsection 306(5) deals with by reducing the exemption test policies in a stated order, lowers the ceiling as well as the coverage.
What the test does not permit is unlimited money. The idea that a person can put any amount into a life insurance contract and have it grow without tax is false, and it is false because of section 306. The exempt test caps the accumulating fund at what a notional contract with a set death benefit would hold, and every dollar past that ceiling is the reason the contract stops being exempt. Holding the highest practical level of control over the capital flow function in one's own affairs, which is what this practice means by Infinite Financial Sovereignty®, includes knowing where that ceiling is and choosing to stay under it.
What can the insurer do to keep a contract exempt?
each one taxed differently
Three ways to reach the value, often confused
- 01An advance, A withdrawal, A surrender
- 02The contractStays intact, under its terms; Value is removed permanently; Ends.
- 03The death benefitReduced while a balance is outstanding; Usually reduced, and not restored later; Ends with the contract.
- 04Can it be undoneYes, by repaying the balance; No, not by paying money back; No, and insurability may not be there again.
- 05TaxNot taxed when made, but it is a disposition; Amounts above the adjusted cost basis can be taxable; Amounts above the adjusted cost basis are taxable.
Most participating whole life contracts give the insurer a contractual right to adjust the contract to keep it exempt, and the two adjustments in ordinary use are an increase in the death benefit and a refund of premium. Both are terms of the contract rather than provisions of the Regulations, so what an insurer may do is read there.
The first adjustment raises the ceiling. Because a new exemption test policy is deemed issued when the benefit on death rises past the 108 percent threshold in subsection 306(3), an increase in the death benefit adds notional contracts on the comparison side, and the real fund has more room beneath them. The cost is a higher amount at risk for the insurer and therefore a higher cost of insurance charged inside the contract, which the owner pays whether or not the extra coverage was wanted.
The second adjustment lowers the real fund. An insurer may refund the part of a premium that would take the accumulating fund over the ceiling, or hold it outside the contract in a side account with its own tax treatment. The money comes back, but it comes back because it could not stay, and an owner who had planned to have it inside the contract has a decision to make with an accountant rather than with the insurer.
The Regulations acknowledge both practices. Paragraph 306(1)(b) requires the forward-looking test for a contract issued after 2016 to be assessed without reference to any automatic adjustments made to keep the contract exempt, which prevents an insurer from relying on its own future interventions to satisfy the expectation today. Subsection 306(8) then supplies the working room: a contract that would cease to be exempt at an anniversary is deemed exempt at that anniversary if it would have been exempt had the anniversary fallen 60 days later, or if the person insured dies on the anniversary or within 60 days after it. Those 60 days are the window in which an adjustment is made.
What happens when a contract is not exempt?
The contract stops being taxed as insurance and starts being taxed each year on its growth, under section 12.2 of the Income Tax Act. Nothing is paid out, no money leaves the contract, and the owner still holds the same document. What changes is that the deferral ends and an annual inclusion in income begins.
Subsection 12.2(1) applies to a taxpayer who holds an interest, last acquired after 1989, in a life insurance policy that is not an exempt policy, leaving aside annuity contracts and the other exclusions the subsection lists. On any anniversary day of the policy in a taxation year, the taxpayer includes in income the amount by which the accumulating fund in respect of the interest on that day exceeds the adjusted cost basis of the interest on that day. Subsection 12.2(11) defines the anniversary day as the day one year after the day immediately preceding the date of issue, and each day at successive one year intervals after it.
Two things follow from that wording. The inclusion is an amount of income without a matching payment, so the tax on it is paid from other resources, and a contract that was funded to the line is by definition a contract whose fund exceeds its cost basis by the most it could. And the inclusion repeats. Each anniversary day produces a new comparison of accumulating fund against adjusted cost basis, and each year's growth inside the contract becomes that year's income.
The Act does not tax the same dollar twice. Under the definition of adjusted cost basis in subsection 148(9), an amount included in income under section 12.2 is added to the adjusted cost basis of the interest, so the next year's comparison starts from a higher base and a later disposition does not tax growth already taxed. That is a mechanical fairness, not a consolation, and the arithmetic on any actual contract belongs to a Chartered Professional Accountant. Whether a death benefit paid under a contract in that position is itself taxable is a separate question, and the ground on how life insurance is taxed in Canada is on the taxability page.
Can a contract that lost its exemption get it back?
read one illustration as two documents
What is guaranteed, and what is not
- 01Cash valueGuaranteed: Set out in the schedule at issue. Not guaranteed: Projected totals, which assume the current scale holds.
- 02Death benefitGuaranteed: Guaranteed, subject to the contract terms. Not guaranteed: Anything the declared dividends add to it.
- 03The annual decisionGuaranteed: A level premium, fixed by the contract. Not guaranteed: Dividends, declared annually and never guaranteed.
Not on the wording this page read. Section 306 of the Income Tax Regulations was read looking for a provision that returns a failed contract to exempt status, and no such provision was found. The condition in paragraph 306(1)(c), that the ceiling was respected at every prior anniversary, carries a single failure into every later reading of the test.
The structure of subsection 306(1) is what makes the status permanent. Exempt is defined at a time, and two of its four conditions look backward. A contract that exceeded the ceiling at one anniversary can never again say that the ceiling was met on all policy anniversaries before the time in question, so it can never again satisfy the definition, however modest its fund becomes later and however much death benefit is added. The Regulations do not provide a cure, a repayment or a fresh start.
The one relief is the 60 day rule in subsection 306(8), and it operates before the failure is recorded rather than after. A contract that would have been exempt had the anniversary fallen 60 days later is deemed exempt at that anniversary, which is what allows an insurer's adjustment inside the window to prevent the failure from ever existing. A contract whose insurer did not act inside the window, or whose owner refused the adjustment, has no second window.
That is the reason the insurer's contractual right to adjust is written into the contract in the first place, and the reason an owner should read that clause before signing rather than after a letter arrives. A separate contract issued later starts its own history under section 306, but it is a separate contract, with its own underwriting, its own cost of insurance at a later age and its own first anniversary, and nothing from the failed contract moves into it.
What changed in 2017, and which contracts stay under the old test?
The exempt test was rewritten for contracts issued after 2016, and a contract issued before 2017 stays under the earlier version unless a change described in subsection 148(11) of the Income Tax Act happens to it. Section 306 of the Income Tax Regulations carries both versions side by side, so the deemed year of issue decides which rules apply.
The differences run through the section. For a contract issued after 2016, subsection 306(3) deems exemption test policies to be issued coverage by coverage rather than for the contract as a whole, and adds a reading for increases in a fund value benefit. Paragraph 306(1)(b) assesses the forward-looking expectation without reference to automatic adjustments. The 250 percent rule in subsections 306(6) and 306(7) carries additional conditions. And section 307 computes the accumulating fund of an exemption test policy on assumptions that differ between the two generations of contract. In broad terms, the later rules leave less room, which is why the date of issue matters to an owner.
Subsection 148(11) is the door between the two regimes. It deems a life insurance policy issued before 2017 to have been issued after 2016 at the particular time when term life insurance under the policy is converted into permanent life insurance under the terms of the policy, or when life insurance that was medically underwritten after 2016 is added to the policy, other than underwriting done only to obtain a reduction in the premium or cost of insurance rates, and leaving aside insurance paid for with policy dividends and coverage that is reinstated. Once that time arrives, the whole contract is read under the later rules, and subsection 306(10) sets out how the exemption test policies are recast at that point.
The practical rule is that an older contract is worth leaving alone until the consequence of touching it has been confirmed. A conversion of term life insurance inside an older participating contract, or an underwritten addition of coverage, is a decision with a tax dimension the owner cannot see on the form. The insurer confirms in writing whether the change engages subsection 148(11), and a Chartered Professional Accountant reads what that means for the owner before anything is signed.
Who this suits, and who it does not
It suits an owner who funds a participating whole life contract toward the line and wants to know what the line is made of and what the adjustment clause is for. It suits a person told that growth inside a contract is sheltered without limit and wants the limit named. It suits a pre-2017 owner weighing a conversion.
It does not suit a person looking for a way to put an unlimited amount into a life insurance contract and defer tax on all of it, because section 306 of the Income Tax Regulations is the reason that cannot be done. It does not suit an owner whose contract has already failed, because nothing on this page reverses that and the correct room for that conversation is an accountant's. And it does not suit anyone who wants a figure for their own contract, because the figure comes from the insurer's reserve calculation and from nowhere else.
Everything here is written by a person paid by commission from an insurer when a contract is issued, and that interest is stated at the foot of every page. A participating whole life contract is insurance and not an investment; its dividends are not guaranteed, its exempt status is a characteristic the insurer maintains under the contract rather than a promise, and the tax consequences of losing it are read with a Chartered Professional Accountant and with nobody else.
A thirty-minute discovery meeting
A first conversation establishes whether this fits. No illustration is prepared and nothing is arranged.
Often the answer is no, and you will hear it during the call rather than in a proposal afterwards.
This form reaches Canadian Wealth Creation Centre Inc. Any meeting, any advice and any insurance product is provided by Canadian Wealth Creation Centre Inc., through its representatives certified by the Autorité des marchés financiers. IBC Financial is the company's education platform: it distributes no product and no financial service, and it gives no individualised advice.
Common questions
What is the exempt test on a life insurance policy in Canada?
What happens if my whole life policy fails the exempt test?
Can a life insurance policy become exempt again after it fails?
What is the 250 percent rule for life insurance?
Does the insurer automatically fix a policy that is about to fail the exempt test?
Is my policy issued before 2017 still under the old exempt test?
Sources
- Income Tax Regulations, C.R.C., c. 945, section 306, exempt policies, English version, Justice Laws Canada, Regulations current to 21 June 2026, last amended 18 June 2026, verified 2026-09-16
- Income Tax Regulations, C.R.C., c. 945, section 307, accumulating funds, English version, Justice Laws Canada, Regulations current to 21 July 2026, last amended 18 June 2026, verified 2026-09-16
- Règlement de l'impôt sur le revenu, C.R.C., ch. 945, articles 306 et 307, French version, Justice Laws Canada, article 306 à jour au 21 juillet 2026, article 307 à jour au 21 juin 2026, dernière modification le 18 juin 2026, verified 2026-09-16
- Income Tax Act, R.S.C. 1985, c. 1 (5th Supp.), section 12.2, English and French versions, Justice Laws Canada, Act current to 21 July 2026, last amended 18 June 2026, verified 2026-09-16
- Income Tax Act, R.S.C. 1985, c. 1 (5th Supp.), subsections 148(9) and 148(11), English and French versions, Justice Laws Canada, Act current to 21 July 2026, last amended 18 June 2026, verified 2026-09-16
About the author
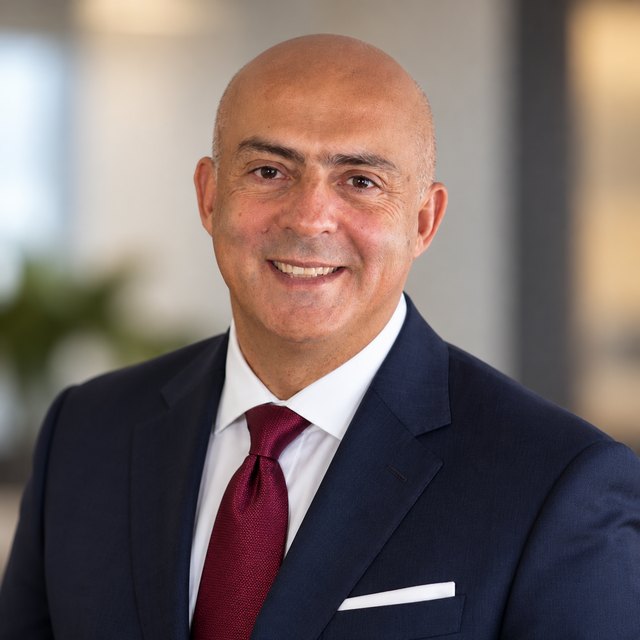
Jose Salloum is a Financial Security Advisor (conseiller en sécurité financière) certified by the Autorité des marchés financiers in Quebec, a Life and Accident & Sickness Insurance Agent licensed by the Financial Services Regulatory Authority of Ontario, and a Life Insurance Agent licensed by the Insurance Council of British Columbia. Licensed since 2001.
He has practised Infinite Banking since 2015 and founded Canadian Wealth Creation Centre Inc., which operates as IBC Financial, in 2016. He holds the Infinite Banking Concepts® Authorized Practitioner certification from the Nelson Nash Institute. That is a private certification rather than a regulatory licence.
IBC Financial is the education platform of Canadian Wealth Creation Centre Inc. This page is general education and not advice on any individual file.
Last reviewed 2026-09-16. By Jose Salloum, Financial Security Advisor.