
Glossary of Canadian Life Insurance Terms
This glossary defines the technical terms used across this site. Each entry states what the term means, where it appears in a contract or on an illustration, and which terms it is commonly confused with.
The Strategy
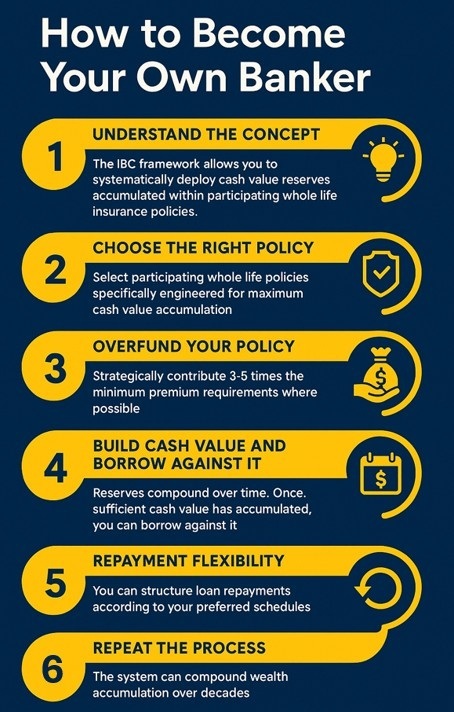
The Infinite Banking Concept® is a strategy that uses a specially designed participating whole life insurance contract as a place to hold and access capital, so the policyowner controls the financing of their own purchases rather than routing every dollar through an outside lender.
The Concept, Explained From the Start
Mostly a way of thinking about who finances your life, and only partly a contract. What it is for, what it requires, and who it does not suit.
Read more
Capital Held Within a Family
What practitioners call a family treasury: how capital is held and lent within a family, where it fails, and what the vocabulary overstates.
Read more
Claims That Should Never Be Made About This Approach
Ten claims commonly made about this approach that are inaccurate, each with the technically correct version, so a reader can tell a description from a pitch.
Read more
Life Insurance Is Not an Investment
Why participating whole life is an insurance product rather than an investment, why people describe it as one anyway, and what the distinction protects.
Read more
What Is Known as The Infinite Banking Concept®: How the Method Works in Canada
What the concept is, how the method works in Canada, what it costs, what it risks, how long it takes and who it suits. Education from IBC Financial.
Read moreWhole Life Insurance
Participating whole life insurance is permanent coverage combining a guaranteed death benefit with a guaranteed cash value, and it may receive dividends declared annually at the discretion of the insurer's board based on the performance of the participating account.
Whole Life Insurance in Canada
The permanent insurance landscape in Canada: participating whole life, non-participating, universal life, term, and how they compare with one another.
Read more
A Policy Advance and Other Credit
A policy advance set beside a secured line, an unsecured line and a collateral loan: who lends, what secures it, who sets the rate, and what each one costs.
Read more
Converting Term or a New Contract
The two routes from a Canadian term policy to permanent coverage: exercising the conversion privilege, or applying for a new contract, and how health decides.
Read more
Life Annuities
What a life annuity is, the main types, how Canadian taxation differs between prescribed and accrual treatment, and what is irreversible about it.
Read more
Participating Life Insurance
What participating life insurance is, how the participating account works, how dividends are declared and used, what it costs, and who it does not suit.
Read more
Participating Whole Life and Universal Life
How participating whole life and universal life differ in Canada: structure, guarantees, who carries the investment risk, and what each does when underfunded.
Read more
Participating and Non-Participating Whole Life Insurance
How participating and non-participating whole life differ: the participating account, why a dividend is never guaranteed, the price gap, and who each suits.
Read more
Term Insurance
What term insurance is, the four common types, how underwriting works, what drives the premium, how much coverage to hold, and when term is the right answer.
Read morePolicy Basics
A participating policy accumulates a contractually guaranteed cash value, while any declared dividends may buy additional paid-up coverage, and the owner may request a policy loan from the insurer against that value under the terms of the contract.
How a Participating Policy Works, Year by Year
What happens inside a Canadian participating whole life contract: where the premium goes, how cash value accumulates, and how dividends are declared and taxed.
Read more
An Advance of the Death Benefit While Living
The terminal illness advance on a Canadian life contract, its medical condition, its real cost to the beneficiary, and the position in Quebec.
Read more
Cash Surrender Value
What cash surrender value is, how it differs from cash value, what surrender charges do, how a surrender is taxed, and what to weigh before ending a contract.
Read more
Contingent Beneficiary
What a contingent beneficiary is, when the designation takes effect, how it differs from a primary designation, and the errors that send proceeds to an estate.
Read more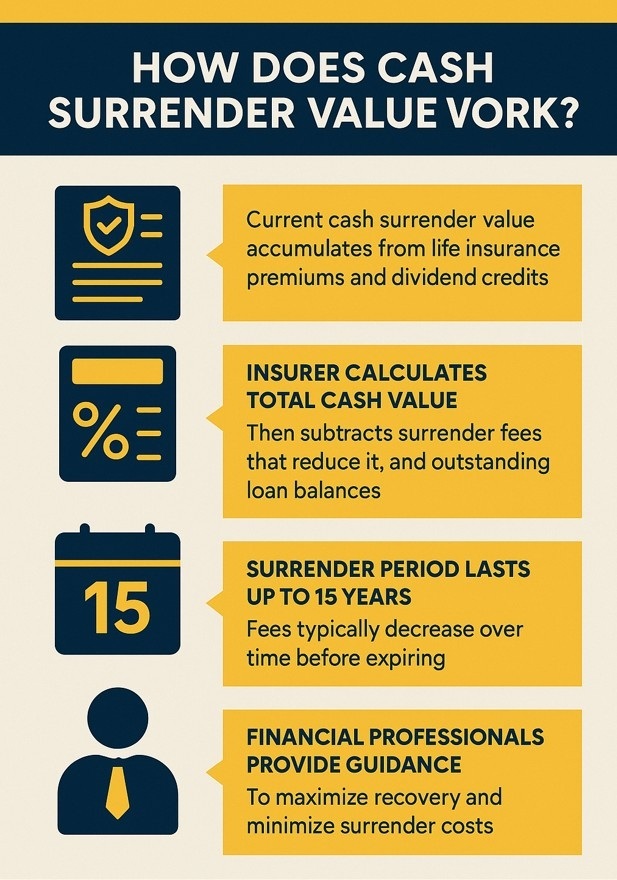
Dividend-Paying Life Insurance
What a life insurance dividend actually is, how the insurer determines it, the five ways it can be used, why it is not a return, and why it is never guaranteed.
Read more
Family History on an Application
How a Canadian application treats a parent's or sibling's illness, which relatives and which ages matter, and what family history does not decide alone.
Read more
Financial Underwriting and Insurable Interest
Why a Canadian insurer asks about income, net worth and purpose before issuing a contract, how those answers set the ceiling, and what the exempt test adds.
Read more
How Many Life Insurance Policies Can You Have?
There is no legal limit on how many life insurance policies you can own in Canada. What limits you is financial underwriting, and how insurers assess coverage.
Read more
Insurance Premium
What a premium actually buys, the components inside it, what drives the price, payment modes and what they cost, and what happens when a payment is missed.
Read more
Is Life Insurance Taxable in Canada?
How life insurance is taxed in Canada: the death benefit, premiums, policy loans, dividends, ownership transfers, corporate ownership and how Quebec differs.
Read more
Life Insurance Underwriting
What happens between a signed Canadian life insurance application and an issued policy: disclosure, medical evidence, financial review and the four outcomes.
Read more
Misrepresentation on an Application
What an incorrect or incomplete answer on a Canadian life insurance application means later: the duty of disclosure, the two year limit, and fraud.
Read more
Paid-Up Additions
What paid-up additions are, how a PUA rider works, what they do to cash value and death benefit, what they cost, and where they stop being useful.
Read more
Policy Loans in Canada
A policy loan is an advance from the insurer secured against the cash value. How the amount is set, how interest accrues, and how it is taxed in Canada.
Read more
Smoker Status and the Premium
How Canadian insurers define smoker status, what the twelve month question covers, how a cotinine test verifies it, and what a wrong answer costs at claim.
Read more
Tax-Deferred Growth
What tax deferral actually is, where it exists in Canada, the difference between deferred, exempt and tax-free, and why deferral is not forgiveness.
Read more
The Civil Code and the Life Insurance Contract
Quebec is the only province where a life insurance contract is governed by the Civil Code. Declaration of risk, contestability, beneficiary, succession.
Read more
The Medical and What It Measures
What the paramedical exam for Canadian life insurance actually measures, who performs it, when an ECG is added, and what an abnormal result leads to.
Read more
Travel, Residency and Occupation
How a Canadian life insurance application prices foreign travel and occupation, and why residency alone decides whether an insurer can issue the contract.
Read more
Waiver of Premium Rider
What a waiver of premium rider does, how the definition of disability decides whether it ever pays, the waiting period, exclusions, cost and who it suits.
Read more
What Is a Policyholder?
Who owns a life insurance contract, how the owner differs from the insured and the beneficiary, and why the distinction matters at the time of a claim.
Read more
When an Application Is Rated, Postponed or Declined
What a rating, a postponement and a decline each mean on a Canadian life insurance application, how a rating is priced, and what options remain afterwards.
Read moreRetirement Planning
Permanent life insurance can sit alongside registered accounts in a retirement plan, holding capital that is not subject to contribution limits, though it serves a different purpose from an RRSP or a TFSA and is not a replacement for either.
Retirement Planning in Canada
How Canadian retirement income is assembled, the order withdrawals should be considered in, and where permanent insurance does and does not fit.
Read more
Business Owners Retirement Plan
How retirement planning differs when the wealth is in the business: the vehicles available, why the exit is the funding event, and what happens if it fails.
Read more
Doctor Retirement Plan
Why retirement planning differs for a Canadian physician: the late start, no employer pension, incorporation, and what each vehicle actually does.
Read more
Insured Retirement Plan
What an insured retirement plan is, why the loan comes from a lender rather than the insurer, what the structure depends on, and how it fails in practice.
Read more
Real Estate Investor Retirement Planning
Retirement when the wealth is in property: the illiquidity problem, the tax bill at death, concentration, and the exit that has to be planned years ahead.
Read moreEstate Planning
At death a Canadian estate faces a deemed disposition of most capital property, and a life insurance death benefit paid to a named beneficiary passes outside the estate, which affects both the tax owing and the liquidity available to pay it.
Estate Planning in Canada: What It Is, How It Works, Importance, Costs
A Canadian guide to estate planning: what it is, the documents required, when to start, what it costs, how trusts work, and how insurance fits inside it.
Read more
A Death Benefit and a Testamentary Trust
How a life insurance death benefit can be directed to a trustee rather than to a person in Canada, what the will must set out, and what a trust costs to run.
Read more
An Estate With Assets and No Cash
An estate can hold a cottage, a farm or a private company and no money for the tax arising at death. What that obligation is, and the routes that exist.
Read more
Asset Protection
What asset protection means in Canada, which protections exist by statute, what structures do and do not achieve, and the timing rule that governs all of it.
Read more
Family Patrimony and the Beneficiary Designation
What Quebec's family patrimony does to a life insurance contract, and how a beneficiary designation behaves at marriage and divorce.
Read more
Generation Wealth Building
How wealth is built and transferred across generations in Canada: what passes outside the estate, the deemed disposition, liquidity, and where insurance fits.
Read more
Taxes on Death Benefits
How death benefits are taxed in Canada: life insurance proceeds, the CPP death benefit, employer death benefits, survivor benefits, and who reports what.
Read more
Will Verification in Quebec and the Death Benefit
In Quebec, will verification replaces probate. What it establishes, its cost in delay rather than fees, and how the death benefit sits outside it.
Read moreBusiness Owners
A corporation may own a life insurance policy on a shareholder or key person, which changes who pays the premium, how the cash value is reported, and how the death benefit is credited to the Capital Dividend Account for distribution to shareholders.
Insurance and Capital for Canadian Business Owners
Why the corporate analysis differs from the personal one: how surplus is taxed while held, what a death benefit does inside a corporation, and where it fails.
Read more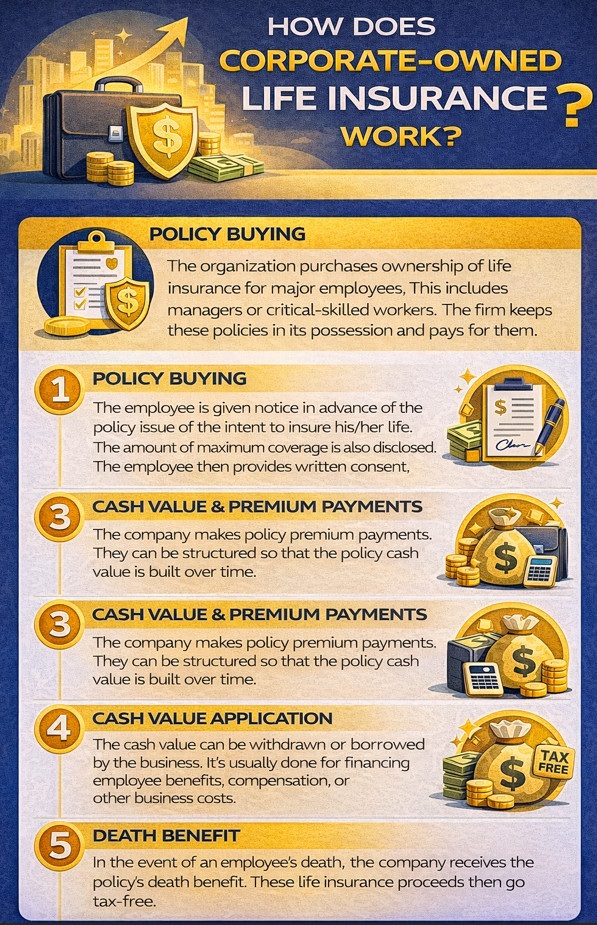
Buying Into a Partnership at the Point of Highest Debt
A partnership buy-in is one purchase, financed, settled in a few months, at the point of highest debt in a working life. What the buyer is actually signing.
Read more
Corporate-Owned Life Insurance (COLI)
How corporate-owned life insurance works in Canada: who owns it, who is named, how the Capital Dividend Account operates, and where structuring goes wrong.
Read more
Cost Per Mile, and the Cost of Capital Nobody Costed
A fleet owner costs fuel, tires and maintenance to the cent. The one line never costed is capital, and the lender's security is the truck itself.
Read more
Dentists and the Equipment Cycle: Who Is Paid Every Time
A dental practice replaces the same equipment several times over a career and finances it every time. Where that interest goes, and who else could receive it.
Read more
Farm Families and the Land That Cannot Be Divided
Nearly all of a farm's value sits in one asset that is also the workplace and the home. What that does to a succession, and where the cash comes from.
Read more
Manufacturers and the Machine That Outlives Its Financing
A plant buys a machine that will run for two decades and finances it over a fraction of that. The mismatch between those two numbers is the conversation.
Read more
Pharmacy Owners, Salaried Pharmacists, and the Capital on the Shelf
A pharmacy holds capital on a shelf, earns much of its revenue on a schedule set by a government, and answers to a banner. Two readers, one page.
Read more
Six Months of Income Against Twelve Months of Cost
A seasonal operator earns in part of the year and pays for all of it. Why the numbers are stable rather than unstable, and what that changes.
Read more
Somebody Else's Calendar: The Refit, the Lease and the Guarantee
A restaurant refits when a franchisor or a landlord says so, not when it is ready. What that timing costs, and where the household sits behind the lease.
Read more
The Accountant Asked to Approve This, and What to Check
A briefing for the professional asked to approve or reject a corporate-owned participating contract: the mechanism, the concessions, and the questions.
Read more
The Contractor With One Client and a Contract That Ends
One client at a time, a contract with an end date, and a day rate that has to cover everything an employer used to. The arithmetic, without rhetoric.
Read more
The Design Practice and the Obligation That Outlives the Work
A design practice delivers a project and keeps an obligation for years afterwards. How claims-made cover, run-off and a staged fee cycle actually interact.
Read more
The Holdback, the Crew and the Money Already Earned
A contractor can be profitable on paper and short at the till, because a holdback keeps money already earned. What that gap costs, and who is paid for it.
Read more
The Incorporated Physician's Corporation, and What Sits Inside It
What happens to the money a physician leaves in the professional corporation, how investment income inside it is measured, and what an exempt contract changes.
Read more
The Real Estate Agent's Year: Lumpy Income, Monthly Bills
Commission arrives in lumps and stops in the quiet months. What a self-employed salesperson can hold that smooths the gap, and what nobody should hold.
Read more
The Small Firm, the Draw, and Money That Is Not the Firm's
A partner draws rather than earns a salary, and holds an account of money that is not the firm's. What both facts do to liquidity in a small practice.
Read more
Veterinarians and What the Practice Is Worth to Anybody Else
A veterinary practice is worth what somebody else will pay for it, and the owner is usually the last person to find out what that number is.
Read more
What Is the Succession Planning Process?
Succession planning covers two questions: who leads the business next, and who owns it next. Most plans answer the first and leave the second undecided.
Read moreMoney Principles
Opportunity cost, compound growth, capital recovery and liquidity are the ideas a reader needs before any product conversation makes sense, because they describe what money does over time regardless of where it is held.
Money Principles
Opportunity cost, compound growth, capital recovery, liquidity and the cost of waiting, each explained on its own without reference to any product.
Read more
A Tax Bill in April
A personal tax balance arrives on a known date. How the instalment system, a line of credit, a payment arrangement and a policy advance each fund it.
Read more
Capital Recovery
What capital recovery means, the capital recovery factor, and how depreciation and the Canadian capital cost allowance relate to it.
Read more
Compound Interest
How compound interest works, the formula and what each term means, why frequency matters, the rule of 72, and the three ways the arithmetic is overstated.
Read more
Opportunity Cost
What opportunity cost means, how it is calculated, explicit and implicit costs, how it differs from sunk cost, and why the alternative must be named.
Read more
Paying for a Renovation
How a Canadian household pays for a renovation: cash, a secured line against the home, unsecured credit, a policy advance, or a collateral loan on a policy.
Read more
Paying for a Vehicle
The four ways a Canadian household pays for a vehicle, compared on where the money comes from, what security is taken, who sets the rate and what each costs.
Read more
The Down Payment
A down payment holds two questions: where capital waits while it is accumulated, and where it comes from on the day. Both, without a product attached.
Read more
The Money Multiplier
What the money multiplier is, how it is calculated, what the reserve ratio does, and why the textbook version does not describe Canadian banking.
Read more
What Are the Fees for a Wealth Manager?
How wealth management is charged in Canada: percentage of assets, hourly, flat and retainer structures, management expense ratios, and embedded costs.
Read more
Why Is Personal Finance Important?
What personal finance covers, where the field came from, the five areas it spans, the order they matter in, and what changes when someone understands it.
Read moreObjections and Risks
Critics of this strategy raise arguments about cost, opportunity cost, comparison framing and the rate at which policies are surrendered, and several of those arguments are correct and are addressed directly here rather than dismissed.
The Honest Case Against, and What It Gets Right
The arguments made against using participating whole life insurance as a place to hold capital, set out in full, including the ones that are correct.
Read more
Is It Legitimate?
Whether The Infinite Banking Concept® is legitimate is three questions at once. The contract is regulated insurance; the selling is what draws criticism.
Read more
Risks and Failure Modes
The ways a participating contract goes wrong in practice: early surrender, lapse with a loan outstanding, overfunding, wrong design, and loss of exempt status.
Read more
The Comparison Question
The usual case for this strategy compares a policy loan with borrowing from an outside lender. For most people the honest comparison is their own savings.
Read more
The Real Costs
What a participating whole life contract costs, why the costs are not itemised the way a fund's fees are, and how to measure them anyway.
Read more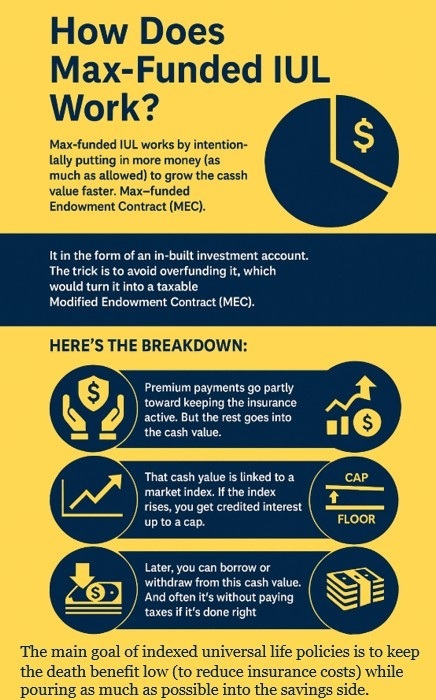
What Critics Get Right
Nine arguments made against using participating whole life insurance to hold capital, each stated at its strongest, and each given a plain verdict.
Read moreFamily Finance
Families face funding decisions across a lifetime, including education, a first home and emergency liquidity, and permanent insurance is one of several ways to hold capital for them, suited to some circumstances and not others.
Family Finance
Household decisions in the order they matter: protecting income, emergency liquidity, education funding, a first home, and where coverage on children fits.
Read more
A Large Sum Arrives, and Nothing Has to Be Decided This Month
A single large sum, one chance to place it well, and a queue of people with opinions. What the arrival actually requires, which is less than it appears.
Read more
Insuring a Child, and What the Contract Is Actually For
A participating contract on a child's life in Canada: who owns it, what it is genuinely for, what it is not, and why the parents come first.
Read more
Requalifying Mid-Career, and the Timeline That Got Shorter
A qualification earned once and earned again costs years of income. What that does to a household balance sheet, and to the arithmetic of the years that remain.
Read more
The First Contract at Twenty-Five
What a permanent life insurance contract taken young does, what age changes in its pricing, and the ordinary reasons a person that age should not proceed.
Read more
The Guaranteed Insurability Option
The guaranteed insurability option on a Canadian life insurance contract: a right to buy more coverage at stated future dates without new evidence of health.
Read more
Two Incomes in the Forties, and Where the Money Goes
A household at its highest ever income can feel poorer than it did at half of it. Where the money goes in the financed decade, described without a lecture.
Read more
University Fees: A Known Cost on a Known Date
Almost no household expense announces itself years ahead. Tuition does, which changes what can be prepared for it and what the containers each do.
Read more
Who Owns a Child's Policy
Who owns a participating contract taken out on a child in Canada, what the owner controls that the child does not, and what changes when ownership transfers.
Read moreLocations
Insurance is regulated provincially in Canada. What an advisor may call themselves, which regulator supervises them, and what happens to an estate all differ by province. These pages set out what is different where you live.
Life Insurance by Province and City in Canada
Insurance is regulated provincially in Canada. Which regulator supervises your advisor, which titles they may use, and what an estate costs all differ.
Read more
Brandon: The Land That Cannot Be Split
Around Brandon the farm is one asset worth many times the family's savings, and the succession question is how the child who does not farm is made whole.
Read more
Burlington: The Second Death, Not the First
Life insurance Burlington planning turns on the second death, when registered accounts settle in one year against a balance sheet that holds no cash.
Read more
Calgary: The Income That Arrives in Lumps
In Calgary a large share of the pay arrives as bonus, shares or a contract payment rather than salary, which makes capital in the gap years the first question.
Read more
Dieppe: The Language the Paperwork Is In
Dieppe lives in French beside a city that works in English, and which language a family's claim is conducted in was settled years before anybody needed it.
Read more
Edmonton: The Pension Is Real, the Capital Is Not
In Edmonton the pension is genuinely good and pays an income for life, and it never becomes a sum the household can direct at a roof, a business or a child.
Read more
Fredericton: One Household, Two Different Risks
In Fredericton one spouse often holds a secure public pension while the other works on contract or on grant money, and the household plans as if both were safe.
Read more
Hamilton: When the Body Is the Income
In Hamilton the earner's body is part of the income, which makes this a question about physical capacity years before it is ever a question about death.
Read more
Kitchener and Waterloo: When the Job and the Savings Are One Company
Technology pay in Kitchener and Waterloo is part salary and part shares, so one employer supplies the income and holds much of the savings at once.
Read more
Laval: The House Is the Balance Sheet, and It Cannot Be Divided
In Laval most of a household's net worth sits in one house, and a great many businesses here are family owned. What both change about liquidity.
Read more
Lethbridge: The Water Travels With the Land
Around Lethbridge the value of farmland rests on an allocation of water attached to it, so dividing the acres can divide the access that made them productive.
Read more
Life Insurance in Abbotsford: The Working Farm Inside a City
An Abbotsford farm is worth more as ground than as an operation. What that does to succession, and how the child who does not farm is made whole.
Read more
Life Insurance in Alberta: Rules, Probate and Who May Advise You
What differs for an Alberta household: the Alberta Insurance Council, a probate fee structure unlike Ontario's, and no provincial title protection statute.
Read more
Life Insurance in Brampton: The Obligations Nobody Wrote Down
A Brampton household often supports people who do not live in it. What happens to obligations nobody put in writing when the income behind them stops.
Read more
Life Insurance in Burnaby: A Home You Own With Other People
In Burnaby the family home is often a strata unit, so the largest thing a household owns is governed with neighbours and cannot be sold in pieces.
Read more
Life Insurance in Coquitlam: The Money the Parents Put In
In Coquitlam a parent's help with a deposit is rarely written down. What that undocumented transfer decides later, and how a family equalises without a sale.
Read more
Life Insurance in Kelowna: Arriving With the Sale Behind You
Kelowna households often arrive holding proceeds from a business already sold, with a short horizon rather than a long one. What changes, and when it fits.
Read more
Life Insurance in Langley: The Business That Ends With You
A Langley trades or service firm is often one person's reputation and licence. When nothing transfers at the end, retirement must be built outside the company.
Read more
Life Insurance in London, Ontario: Money Left Over and No Decision Made
A London household often has two secure incomes, a pension, a house it can afford, and a monthly remainder nobody has ever assigned to anything.
Read more
Life Insurance in Longueuil: One Industry, and a Pension That Is a Promise
A South Shore household often has its salary, its pension and its neighbours' jobs in one industry. What that concentration changes about a financial plan.
Read more
Life Insurance in Manitoba: The Province That Abolished Probate Fees
Manitoba abolished probate fees, which removes the estate-cost argument entirely. What that changes about naming a beneficiary when the fee is nil.
Read more
Life Insurance in New Brunswick: Title Protection and Two Official Languages
New Brunswick is Canada's only officially bilingual province and one of three with title protection legislation. What both mean for a household here.
Read more
Life Insurance in Quebec: A Different Legal System Entirely
Quebec operates under a different legal system, not merely different rules. What that changes for insurance: the AMF, spousal designations and notarial wills.
Read more
Life Insurance in Richmond: The Name You Put on the Title
Adding a parent's or an adult child's name to a title is the estate plan many Richmond families believe they have. What that signature did and did not do.
Read more
Life Insurance in Sherbrooke: Smaller Numbers, and Why the Order Matters More
A Sherbrooke household usually earns less and paid far less for its house than one closer to Montreal. What a modest, steady surplus should refuse first.
Read more
Life Insurance in Surrey: The Household Three Generations Deep
Surrey households are younger, more often owner operated, and more often three generations deep. What that changes about who a death benefit is actually for.
Read more
Life Insurance in Vancouver: What Is Different in British Columbia
What differs for a Vancouver household: the Insurance Council of British Columbia, probate fees rather than an estate tax, and wills variation.
Read more
Life Insurance in Victoria: The Household That Has Already Stopped Building
Victoria holds a large share of households drawing income rather than building it. For that reader the honest answer to this method is usually different.
Read more
Lévis: The Career, the Crossing, and No Sum to Direct
A Lévis household often earns, saves, borrows and insures inside one institution. What life insurance in Lévis answers when nothing sits outside it.
Read more
Markham: The Money That Never Leaves the Company
In Markham the household surplus usually sits inside a private corporation, which changes who should own a life insurance contract and what happens at death.
Read more
Mississauga: Capital an Owner Controls
In Mississauga the reader usually owns the company rather than working for one, and that single fact changes who owns the contract and who is paid.
Read more
Moncton: Income Without Capital Behind It
In Moncton the house is affordable enough that it is not the problem. The problem is that two working salaries can sit behind almost no capital at all.
Read more
Montreal: Where a Renting City's Money Actually Goes
A Montreal household often rents, keeps its surplus at a caisse, and holds its wealth as cash flow rather than in property. What that changes.
Read more
Oakville: Pay You Have Not Been Given Yet
Life insurance Oakville planning starts with pay not yet delivered: unvested shares, options, and a bonus for a year already worked but not yet decided.
Read more
Ottawa and Gatineau: Living in One Province, Working in Another
Thousands in the National Capital Region live on one side of the Ottawa River and work on the other. Which province governs insurance, pensions and an estate.
Read more
Provinces Where This Practice Is Not Licensed
The provinces and territories where neither Jose Salloum nor the firm holds a licence, what that means for you, and how to find an advisor who is licensed.
Read more
Quebec City: Beyond an Indexed Pension
The default reader here holds a defined benefit pension, which answers one question completely and leaves a different set of them entirely untouched.
Read more
Red Deer: When Every Customer Slows at Once
In Red Deer an owner rarely loses one customer, because the whole customer base sits in one industry and every account slows in the same quarter.
Read more
Saguenay: Distance Changes What Capital Is For
A Saguenay estate is usually modest in dollars and spread across several cities. Life insurance in Saguenay is a liquidity question before it is a size one.
Read more
Saint John: One Employer Holds All Three
In Saint John a household's income, its benefits and often its pension all rest on one employer in one industry, and a decision made elsewhere ends all three.
Read more
Terrebonne: The Decade the Mortgage Is Largest and the Savings Smallest
In Terrebonne the mortgage is largest and the savings thinnest in the same decade. What a household at full leverage should settle before anything else.
Read more
Toronto: How to Stop Financing Your Life Through Someone Else
A Toronto household pays interest to lenders for thirty years and never sees it again. Whether that interest could stay in the family instead of leaving.
Read more
Trois-Rivières: A Pension That Is Owed Rather Than Held
In Trois-Rivières many retirements rest on a plan an employer still owes. What a household controls when the promise sits on another balance sheet.
Read more
Vaughan: The Year the Work Stops
Life insurance in Vaughan, where the family building firm is the whole balance sheet and its value depends on one person still being able to run the work.
Read more
Windsor: A Household on Two Sides of a Border
Thousands of Windsor households earn on one side of the border and spend on the other, which produces questions no other page on this site touches.
Read more
Winnipeg: The House Is Paid For and the Estate Is Thin
In Winnipeg an ordinary income can own a house outright, which removes the usual estate problem and quietly exposes the different one sitting behind it.
Read moreTerms are admitted here only once at least two articles need them. A definition that only one page uses belongs inside that page.
The terms
Adjusted cost basis. The tax cost of a policy to its owner, and the figure that decides how much of any amount taken out is taxable.
Capital Dividend Account. The notional account of a private corporation through which a death benefit can reach shareholders without income tax.
The exempt test. The calculation that decides whether a policy accumulates value without annual taxation, and the reason deposits are capped.
Dividend scale. The assumptions behind every non-guaranteed figure on a participating illustration.
Why this section is not indexed
A glossary competes with the articles that define the same terms in context. It is kept here for readers who arrive at a word they do not recognise, and it is not offered to search engines as an alternative to the pages that do the teaching.
How these entries are written
Each states what the term means, in one sentence, before anything else.
Then where it appears in a contract or on an illustration, because a reader who meets a term has usually met it on a document rather than in the abstract.
Then what it is commonly confused with, since most of the difficulty in this subject is two similar words carrying different consequences.
And which articles use it, so a reader can return to the page that does the teaching rather than staying in a list of definitions.
What a glossary cannot do
It cannot tell you whether any of this suits you. A definition is context-free by design, and every question worth deciding depends on facts about a household that no definition contains.
Nor is it a substitute for the contract. Where a definition here and a policy differ, the policy governs, and the definitions are written to help a reader understand their own document rather than to replace it.
Why terms are admitted slowly
A glossary assembled ahead of the content it serves is a keyword list.
Entries appear here only once at least two articles need them, and each runs to enough length to be worth a reader's time. A definition that only one page uses belongs inside that page, where it has the context that makes it usable.
Which means this section will stay small. Most of the terms on this site are explained where they arise, in the article that needed them, and that is the better place for them. The four here earned separate pages because they recur across sections and because readers meet them on documents before they meet them in an argument.
If a term you need is missing
It is probably defined inside an article. The search on this site covers the full text of every page, and the term will usually be found in the first paragraph of the section that uses it.
And if it is genuinely absent, that is worth telling us. The contact details are at the foot of every page, and a term that a reader had to look elsewhere for is a gap in the writing rather than in the glossary.
Where these terms come from
All four are Canadian. The adjusted cost basis and the exempt test come from the Income Tax Act and its regulations. The Capital Dividend Account is a provision of the same Act applying to private corporations. The dividend scale is an insurer's own construct rather than a statutory one.
None transfers from American material. The United States uses a different regime for the same underlying questions, and a reader who arrived here from an American article about modified endowment contracts or section 7702 has been reading about rules that do not apply.
Which is part of why the entries exist. Most of the freely available writing on these subjects is American, the vocabulary overlaps enough to be misleading, and a Canadian reader can spend a long time absorbing a framework that will not describe their own contract.
The order worth reading them in
The exempt test first, because it explains why a Canadian policy is shaped the way it is and why deposits are capped.
Then the adjusted cost basis, which decides what any of the value costs to reach.
Then the dividend scale, which governs everything on an illustration that is not guaranteed.
And the Capital Dividend Account last, since it applies only where a corporation owns the contract and is the narrowest of the four.
A thirty-minute discovery meeting
A first conversation establishes whether this fits. No illustration is prepared and nothing is arranged.
Often the answer is no, and you will hear it during the call rather than in a proposal afterwards.
This form reaches Canadian Wealth Creation Centre Inc. Any meeting, any advice and any insurance product is provided by Canadian Wealth Creation Centre Inc., through its representatives certified by the Autorité des marchés financiers. IBC Financial is the company's education platform: it distributes no product and no financial service, and it gives no individualised advice.
Common questions
Why does this glossary only contain four terms?
Does an American life insurance glossary apply in Canada?
What do I do if the term I need is not in this glossary?
If a definition here and my policy disagree, which one governs?
In what order should I read these entries?
Which of these terms are set by law and which are set by the insurer?
Why is a definition not enough to decide anything?
Where do these terms appear on my policy documents?
Last reviewed 2026-08-21.