

Whole Life Insurance in Canada
Whole life insurance is permanent life insurance: it stays in force for life while the premiums are paid, with a level premium and a guaranteed cash value schedule set out at issue. A participating policy may also receive dividends, which the insurer's board declares each year and never guarantees. It costs more than term life insurance for the same death benefit and suits a need that never ends, such as estate liquidity or a lifelong dependant. For a need with an end date, term life insurance usually fits better.
Whole life insurance is permanent life insurance. It stays in force for your whole life as long as the premiums are paid, usually with a level premium, and it builds a cash value on a schedule the insurer guarantees in writing when the policy is issued. A participating policy may also receive dividends, which the insurer's board declares each year and never guarantees.
It costs more than term life insurance for the same death benefit, because it is built to pay out whenever death occurs, not only within a set period. That makes it the right tool for a need that never ends, such as estate liquidity, a dependant who will always need support or a corporate obligation, and the wrong tool for a need with an end date, where term life insurance usually fits better.
This page covers the products themselves: what exists, how each behaves, what it costs, how it is taxed in Canada, and how to choose. The product this practice works with is set out on participating life insurance, temporary coverage on term life insurance, and insurance against living too long on life annuities. Comparisons with things that are not insurance, such as a registered account or a portfolio, are on objections and risks.
What is whole life insurance?
It is a contract with an insurer to pay a death benefit whenever the insured person dies, in exchange for premiums. The premium is usually level for life or for a set number of years, and the death benefit is stated in the contract. What sets whole life apart from term is that it never expires while the premiums are paid, and that it builds a cash value along the way.
The cash value follows a schedule printed in the policy, year by year. That schedule is guaranteed: it is a contractual obligation of the insurer, and it does not depend on investment results, on a dividend or on any assumption made at the time of sale. You can reach the value during your life through a policy loan from the insurer, or take it by surrendering the policy, which ends the coverage.
Whole life comes in two forms. A participating policy shares in the results of the insurer's participating account, and when the board declares a dividend, the policy receives a share, often used to buy additional paid-up coverage. A non-participating policy receives no dividend; what it guarantees is what it does, and it is priced on that basis.
Neither form is better in the abstract. Participating offers the possibility of values above the guarantees and charges for the structure that makes it possible. Non-participating offers certainty and less upside. The mechanics inside a participating policy, year by year, are in policy basics.
How do the main types of life insurance compare?
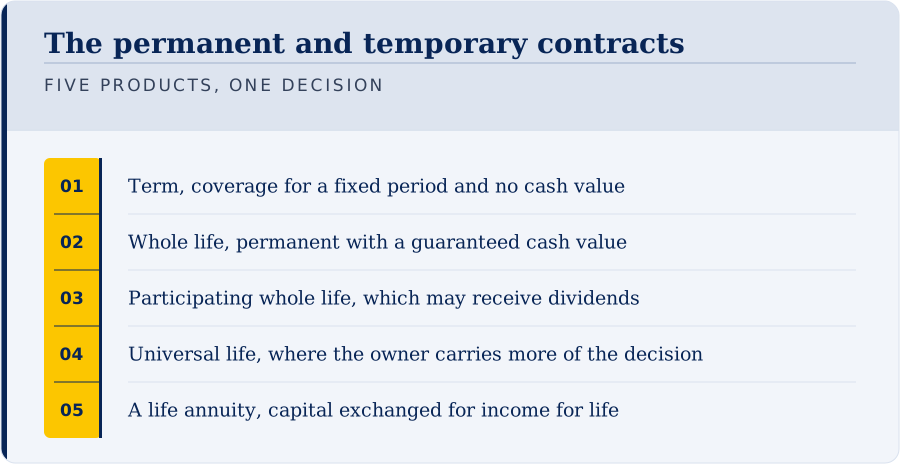
Every life insurance product answers one of two questions: what happens to the people who depend on you if you die, or what happens to you if you live longer than your money. Within the first question, the difference is how long the coverage lasts and who carries the risk. Here are the six products side by side.
| Product | How long it lasts | Cash value | What is guaranteed | Usually suits |
|---|---|---|---|---|
| Term life insurance | A set period, often 10 or 20 years, renewable at a higher premium | None | The death benefit during the term | A need with an end date, at the lowest cost |
| Term to 100 | To age 100, with a level premium | Generally none or minimal | The death benefit | Permanent coverage without accumulation |
| Non-participating whole life | For life | A guaranteed schedule | Premium, death benefit and cash values | Permanent coverage with certainty |
| Participating whole life | For life | A guaranteed schedule, plus dividends when declared | Premium, death benefit and cash values; dividends are not guaranteed | Permanent coverage with a value you can use during life |
| Universal life | For life, if funded enough | Depends on the investment options chosen and the charges | Depends on the design; much less than whole life | An owner who wants flexibility and accepts the investment risk |
| Life annuity | Pays for as long as you live | Generally none once purchased | The income payments | Protection against outliving your savings |
The table shows attributes, not a winner. Each product does one job well, and the mistakes in this market come from using one product for another product's job, not from any product being bad.
Is your need temporary or permanent?
This is the question that comes before any product. A temporary need has an end date: a mortgage that will be paid off, children who will become independent, a business loan with a final payment. Coverage for a set period, at the lowest cost for the amount of protection, fits it, and nothing needs to accumulate.
A permanent need does not go away: a tax bill that arrives at death whenever death occurs, a dependant who will always need support, an estate that will need cash to settle, a corporation that will owe something whenever the shareholder dies. Coverage that never expires fits it, priced accordingly, and building a value along the way is a feature of that coverage.
Getting this wrong is the most expensive error available, in both directions. Permanent coverage bought for a temporary need costs far more than it had to. Term coverage bought for a permanent need expires, usually at the age when replacing it is hardest or impossible.
Often the honest answer is both: a large term policy across the years of highest obligation, with a smaller permanent policy underneath for the part that never ends. That shape suits many families, and it is proposed less often than it should be, simply because it is less decisive than recommending one product.
Term life insurance
declared annually, never guaranteed
How a policy dividend is decided
- 01A distribution from the insurer's participating account
- 02Declared annually at the discretion of the board
- 03Based on investment results, claims experience and expenses
- 04It is not interest and it is not a return
- 05It is never guaranteed, in any year of the contract
Term life insurance covers a stated period, typically ten or twenty years, and is usually renewable and convertible under the contract's terms. It gives the most protection per dollar, and it is easy to compare between insurers, because the product is close to a commodity and its guarantees are simple.
What it does not do is accumulate value or continue indefinitely. Renewal premiums rise steeply at each renewal, and by the second or third renewal the cost is often prohibitive. That is not a defect; it is how the product stays cheap in the years you need it most.
The feature that matters most is the conversion privilege, which most Canadian term policies carry: the right to exchange the term policy for permanent coverage without new medical evidence, up to an age stated in the contract. It is valuable precisely when your health has changed, and it expires quietly. The conversion window often closes years before the term itself ends, and it cannot be added after the policy is issued.
If you hold term life insurance, find two dates today: the expiry and the conversion deadline. The two routes from term to permanent coverage are compared on converting term or a new contract.
Participating and non-participating whole life
A participating policy belongs to a block of policies whose premiums, claims, expenses and investment results are tracked in the insurer's participating account, kept separately from the insurer's other business. When the results of that account allow it, the board declares a dividend, and each participating policy receives a share.
Dividends are never guaranteed. The board declares them each year at its discretion, and the scale has moved in both directions over the decades. What the policy guarantees is its schedule of cash values, its death benefit and its premium. An illustration that holds today's dividend scale for forty years is showing an assumption, not a forecast.
What happens to a dividend depends on the option you choose: buying paid-up additions, reducing the premium, accumulating on deposit with the insurer, or paying in cash. Each has a different effect on the policy and on its tax treatment, set out on the dividend options.
A non-participating policy is simpler. There is no dividend and no discretion: the premium, the death benefit and the cash values are what the contract says, and it usually costs less than a participating policy with the same death benefit. What it gives up is the possibility of values above the guarantees.
Which suits you depends on what the policy is for. The trade between the two is set out without a verdict on participating and non-participating.
Universal life
Universal life is permanent coverage in which the cost of insurance and the accumulating value are separated and visible, and the owner chooses among investment options the insurer offers. The real difference from whole life is not the returns. It is who carries the decisions.
In whole life, the insurer decides how the underlying assets are managed and guarantees the values written into the contract. In universal life, the owner chooses, and the outcome follows from those choices and from the charges the policy deducts along the way.
It suits an owner who wants transparent charges, flexible funding and control over the investment options, and who is comfortable carrying the consequences of that control. It goes wrong when a policy is funded on optimistic assumptions that do not hold, which can later require much higher deposits or lead to a lapse. The flexibility that helps in a good decade becomes an exposure in a poor one.
The two permanent designs, built on opposite principles, are compared attribute by attribute on participating whole life and universal life.
Life annuities
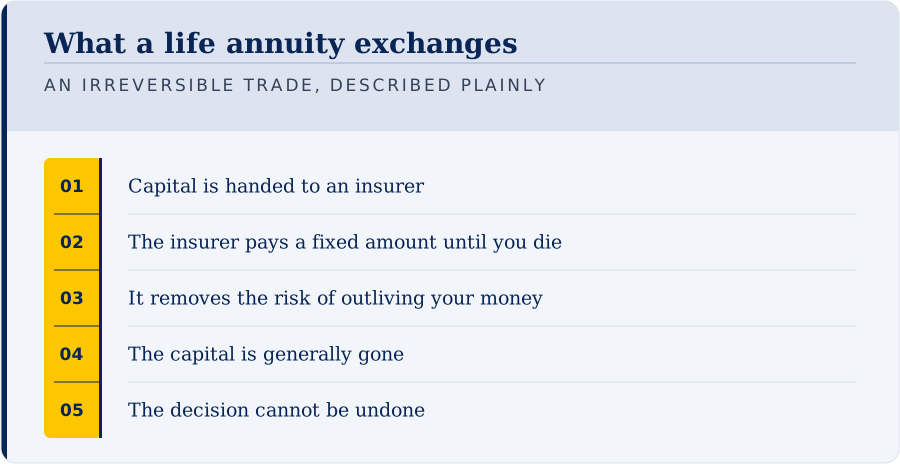
A life annuity reverses the arrangement: you hand capital to an insurer in exchange for an income that continues for as long as you live. It belongs in this section because it is an insurance contract, and because it answers the question life insurance does not: what happens if you live longer than your money.
Payments normally end at death unless you chose a guarantee period, a joint option that continues payments to a surviving spouse, or a refund feature. Each of those protects your beneficiaries and lowers the income. The capital you hand over is generally gone, and the decision cannot be reversed once the annuity is in force.
Underwriting runs in reverse on an annuity. Impaired health can produce a higher payment, because the insurer expects to pay for a shorter time, and that is worth raising rather than concealing.
Life insurance and a life annuity are often discussed as alternatives when they address opposite risks. A family concerned about both may need both, and a comparison that treats them as competitors has misunderstood the question.
How does a policy loan work on whole life?
an irreversible trade, described plainly
What a life annuity exchanges
- 01Capital is paid to an insurer
- 02The insurer pays income for life, on the contract's terms
- 03It removes the risk of outliving the money
- 04Nothing at death, unless a guarantee was bought
- 05Once payments begin, the choice is generally permanent
Once a whole life policy has cash value, you can ask the insurer for a policy loan. The insurer lends you money from its own funds and holds your cash value as security, so there is no credit application and no question about what the money is for. The cash value stays in the policy and keeps being administered under its terms while the loan is outstanding.
The insurer charges interest at a rate it sets and can change. There is usually no fixed repayment schedule, and interest you do not pay is added to the loan, usually at each policy anniversary. The death benefit is reduced by the balance for as long as it stands, and it comes back as you repay.
Two consequences deserve respect. In Canada a policy loan is a disposition, so the part above the policy's adjusted cost basis is taxable income in the year you receive it. And if the debt grows until it reaches the cash value, the policy lapses, which ends the coverage and can create tax in a year with no cash to pay it. How a loan behaves is set out on a policy loan and other credit.
What does the insurer actually promise?
Each product carries a different promise, and naming it clears up most of the confusion. On term life insurance, the insurer promises to pay a stated amount if death occurs within a stated period. On whole life, it promises to pay a stated amount whenever death occurs, and to hold a schedule of guaranteed values in the meantime.
On participating whole life, it promises all of that, plus a share in the participating account, distributed at the board's discretion and never promised in amount. On a life annuity, it promises to pay a stated income for as long as the annuitant lives, however long that is.
Each promise depends on the insurer's solvency, none is backed by any government, and Assuris stands behind them within its published limits.
What does whole life cost, and what do you give up?
The premium is only part of the cost. The rest is what each product asks you to give up. Term life insurance costs its premiums and gives nothing back if you outlive it. That is not a defect; it is why term is cheap.
Participating whole life costs substantially more for the same death benefit. In its early years, most of the cost of putting the policy in force is recovered through lower cash values, so leaving in the first several years returns less than was paid in. The schedule in the policy shows exactly how much less, year by year, before you sign.
Universal life costs the flexibility it grants. You direct the investment side, which means you carry its results: weak performance or rising charges can require higher deposits later or put the coverage at risk. A life annuity costs the capital itself, irreversibly, in exchange for an income that cannot run out.
Each trade is real and none is hidden. A description of any of these products that does not name what it costs you has described only half of it.
The most useful cost question is simple: what would term life insurance cost for the same death benefit? Ask it even when permanent coverage is being proposed. The difference is the price of permanence, and you are entitled to see it.
How much coverage do you need?
a pooled account, managed by the insurer
What stands behind a participating contract
- A participating contractOne account stands behind every contract of this class.
- Premiums are pooledInto one account, not one of your own.
- The insurer manages itInvestment, claims and expenses run through it.
- Policyholders may share in the resultWhat the account earns after claims and expenses.
- The share is declared annuallyAt the board's discretion, and never guaranteed.
The amount is a larger decision than the type, and it is settled with arithmetic, not preference. Work through these in order:
- the debt that would remain, including the mortgage;
- the income that would need replacing, and for how many years;
- specific obligations, such as education or a dependant needing lifelong support;
- what already exists: group coverage through work and any individual policies;
- what would be available: savings, a surviving partner's income, survivor benefits.
Illustrative example. Assume a mortgage of $350,000, an income of $70,000 a year to replace for ten years, and $80,000 set aside for two children's education: $1,130,000 in all. Assume group coverage of $300,000 and savings of $50,000. The gap is $780,000. The figures are assumptions for the arithmetic, the replacement income is not discounted or adjusted for inflation, and your own figures will differ; the method is what carries over.
Round the gap up. At term prices the cost of a little extra is small, and the cost of being short falls on someone else. Remember too that group coverage usually ends with the job, often at the moment a family is most exposed.
And insure the partner who is not paid. Their work would have to be replaced or absorbed, and the family's finances change materially either way. The right figure is not zero, which is what many families choose without noticing.
How do you compare two policies fairly?
The most common error in this market is comparing projected values from two insurers, which compares two sets of assumptions rather than two contracts. Start with the guaranteed columns. They are contractual, and if one policy guarantees more for the same premium, that is a real difference.
Then look at what each projection assumes. The projected column adds an assumed dividend scale, and two insurers assuming different scales will show different values from similar policies. That tells you about the assumptions, not about the contracts. Ask about each insurer's current scale and how it has moved; a scale that has moved is ordinary, and a presentation that never mentions it is not.
Compare the design as well as the product. Two policies from the same insurer, funded identically, can reach very different values in year five depending on how the premium is split between base coverage and paid-up additions. The one that looks worse in year five may be the better policy for its purpose.
Ask what happens if the premiums stop in year two, year five and year ten. The answer at each point tells you more about the contract than any projection.
Finally, ask what the advisor is paid on the policy proposed and on the alternative. The answer, and the reaction to the question, tell you a good deal.
Which riders matter?
Riders attach to a base policy and are chosen at issue, usually once and for good. Most are inexpensive, and a few change what the policy can do:
- Convertibility on a term policy, which preserves the right to permanent coverage without new medical evidence.
- A paid-up additions rider on a participating policy, generally needed to pay in more than the scheduled premium; the details are on paid-up additions.
- Waiver of premium, which keeps the policy in force if the insured becomes disabled and addresses the most common cause of a lapse.
- A term rider on a permanent policy, which raises the death benefit during the heavy years at term prices, and is why an illustration's death benefit can step down partway through.
- Guaranteed insurability, which allows coverage to be increased later without medical evidence.
Child riders and accidental death riders are often sold and rarely material, because neither covers a risk of the size the base policy covers. For each rider, ask what it costs each year and what it prevents, and decline the ones that fail that comparison.
Why do two people pay different premiums?
Underwriting sets the price on every product here except an annuity, where it works in reverse. The insurer is estimating the probability of a claim within the period it is pricing, and every question on the application serves that estimate.
What moves the price most is age, then smoking status, then health established at underwriting, then family history. Two of those are fixed by the time anyone applies, and one is a habit. Rate classes differ substantially: preferred against standard, on identical coverage, is a real difference in premium.
Disclose everything, including what seems unimportant. A material misstatement can let the insurer void the policy during the contestability period set by provincial law, and the claim is then refused at the moment your family needs it. That loss is far larger than any rating the omission avoided.
A rating is not always permanent. Where it was applied for a condition since resolved or now well controlled, many insurers will reconsider on request. Few people ask, and it costs nothing to ask.
Who supervises insurers, and what stands behind the guarantees?
and what it ends
What a surrender actually pays
- 01The cash surrender valueAs the contract sets it for that year.
- 02Plus any dividends on depositAnd other amounts the contract adds.
- 03Less any policy loanWith the interest owed on it.
- 04What reaches youTax turns on the gain over the adjusted cost basis, not on the cheque.
Every guarantee in a policy is a contractual obligation of the insurer that issued it, and it depends on that insurer staying solvent. None of it is backed by any government.
Solvency supervision depends on where the insurer is chartered. Federally incorporated insurers are supervised by the Office of the Superintendent of Financial Institutions. Insurers incorporated in a province are supervised by that province's regulator, such as the Autorité des marchés financiers for insurers chartered in Quebec. How insurance is sold, and the licensing of the people who sell it, is regulated provincially wherever the insurer is chartered.
If a member insurer fails, Assuris protects the higher of $1,000,000 or 90% of the death benefit, and the higher of $100,000 or 90% of the cash value, calculated after any policy loans (Assuris). Assuris is funded by the industry. It is meaningful protection, and it is not deposit insurance or a government guarantee.
Before relying on a guarantee meant to last fifty years, check the insurer's financial strength rating, and remember that a rating is an opinion about the future, not a promise about it.
How is whole life insurance taxed in Canada?
Growth inside a permanent policy is not taxed each year while the policy stays exempt under section 306 of the Income Tax Regulations. For policies issued after 2016, the test compares the policy with a benchmark endowment at age 90 paid over eight years. Insurers design and administer policies to keep them inside the test, which is also why a policy cannot be funded without limit.
A policy that is not exempt is taxed differently: under section 12.2 of the Income Tax Act, its growth is included in the owner's income as it accrues, year by year. That is why the exempt status matters so much, and why it is monitored by the insurer rather than left to chance.
Taking value out during life is a disposition under section 148 of the Income Tax Act. A policy loan, a withdrawal or a surrender is taxed on the part above the policy's adjusted cost basis, in the year it happens, as ordinary income. The adjusted cost basis usually rises in the early years and falls later, so a loan that is tax free early can be partly taxable decades later.
A death benefit paid to a named beneficiary is generally received free of income tax, paid directly and outside the estate. That matters for both tax and liquidity, and it is covered in estate planning.
When a corporation owns the policy and receives the death benefit, its capital dividend account is credited with the death benefit minus the policy's adjusted cost basis, under subsection 89(1) of the Income Tax Act. The corporate analysis changes substantially and is treated with business owners. None of this is tax advice; confirm your own situation with a tax professional.
What usually goes wrong?
Rarely the products. Almost always the match between product and need. Six patterns come up again and again:
- Permanent coverage bought for a temporary need, which means paying for a lifetime of coverage to protect an eighteen-year mortgage, or buying less coverage than the need requires.
- Too little coverage, because premium was the only number compared. Premium measures what you can afford this month, not whether the policy is large enough to do its job.
- Skipping convertibility to save a little, and losing the option that mattered once health changed.
- Group coverage standing in for a plan. It usually ends with the job, at the moment a family is most exposed.
- Funding that an ordinary year cannot sustain. Stopping partway is worse than never starting, because early exit returns least and can create a taxable amount.
- The product chosen before the need was named, which is the error the other five come from.
The correct order is the need, whether it ends, the amount, what can be sustained, and only then the product. Ask whether the need and the amount were written down before any product was named, and ask to see where.
What should you check on the policies you already own?
Most readers of this page already hold coverage, and the most useful work is checking it, not buying something new. It takes about an hour:
- What you have: type, amount, and whether it expires.
- If it is term, the expiry date and the conversion deadline, which usually comes first.
- The beneficiary designation, primary and contingent, and whether it is revocable or irrevocable.
- Whether group coverage through work is doing the job you think it is.
- On a permanent policy, one statement a year: guaranteed value, total value, any policy loan and the dividend applied.
- Who services the policy now.
- Whether someone in your family knows the policy exists.
A revocable beneficiary designation can usually be changed at any time, at no cost. An irrevocable designation cannot be changed without the beneficiary's consent, and in Quebec a designation of a married or civil union spouse is irrevocable unless it states otherwise. A named beneficiary receives the proceeds directly, in weeks and outside the estate, and where the person named falls within a class protected by provincial law, the proceeds may also be beyond the reach of creditors. That depends on the province and on when the designation was made, so confirm it where you live.
The most common finding is a designation that reflects a family which no longer exists. Correcting it is often one form, and it is among the most valuable hours available anywhere in this subject. This practice earns nothing from any of these checks.
Where to go next in this section
Four comparison pages set out attributes rather than verdicts, because a comparison that announces a winner has stopped comparing: participating whole life and universal life, participating and non-participating, a policy loan and other credit, and converting term or a new contract.
The mechanics inside a policy, including cash value, dividends, policy loans, the adjusted cost basis, underwriting and beneficiary designations, are in policy basics.
Comparisons against anything that is not insurance, and the serious arguments against permanent coverage, are in objections and risks. Anything that holds only for someone using a policy within the approach set out by Nelson Nash is in the Infinite Banking section.
And before any of that, one question: does the need end? If it does, the answer is term life insurance, and this site will say so. If it does not, the answer is permanent coverage of some kind, and the rest of this section helps you choose which. Take the time to answer it in writing, with the amounts, before you look at a single illustration; everything after it becomes easier.
A thirty-minute discovery meeting
A first conversation establishes whether this fits. No illustration is prepared and nothing is arranged.
Often the answer is no, and you will hear it during the call rather than in a proposal afterwards.
This form reaches Canadian Wealth Creation Centre Inc. Any meeting, any advice and any insurance product is provided by Canadian Wealth Creation Centre Inc., through its representatives who are licensed in the client's province. IBC Financial is the company's educational website: it distributes no product and no financial service, and it gives no individualised advice.
How Canadians Choose the Right Whole Life Contract
Participating or not, whole life or universal life, term or permanent: the choices that decide what you will own for decades, laid out plainly before anyone asks you to sign.
| A Policy Advance and Other Credit UPDATEDPolicy loan, home equity line, unsecured credit or a collateral loan: who lends, what secures it, how each is taxed in Canada, and what to compare. | Read more |
| Converting Term Life Insurance or a New Contract UPDATEDConvert your term life insurance or apply for a new permanent policy? How conversion works in Canada, when to compare, and when to do neither. | Read more |
| High Cash Value Life Insurance in Canada: How It Is Designed NEWHigh cash value life insurance is a design, not a product: how Canadian participating whole life is built for early cash value, its limits, costs and uses. | Read more |
| Life Annuities UPDATEDHow a Canadian life annuity turns savings into income for life, how it is taxed, what you give up, and the written quotes to compare before you buy. | Read more |
| Participating Life Insurance UPDATEDHow participating whole life works in Canada: what the contract guarantees, how dividends are set, what it costs, how borrowing works, and who it does not suit. | Read more |
| Participating Whole Life and Universal Life UPDATEDParticipating whole life or universal life in Canada? Guarantees, charges, who carries which risk, policy loans, tax, and when each one tends to fit. | Read more |
| Participating and Non-Participating Whole Life Insurance UPDATEDParticipating vs non-participating whole life in Canada: what each guarantees, dividends and bonuses, cost, loans, tax, and what to ask the insurer. | Read more |
| Term Life Insurance UPDATEDWhen term life insurance is the right choice in Canada, how it compares with permanent coverage, how renewal and conversion work, and what to check first. | Read more |
| The Dividend Options and What Each One Does to the Contract UPDATEDDividend options on a specially designed, high-cash-value, participating whole life insurance policy, and what each does to death benefit, cash value and tax. | Read more |
Common questions
What is whole life insurance, in plain words?
What is the difference between whole life and universal life?
Is term life insurance a worse product than permanent insurance?
What is the difference between participating and non-participating whole life?
Can I convert a term life insurance policy to permanent coverage later?
How do I compare two insurance policies fairly?
Should I buy term life insurance or whole life?
Is an annuity an alternative to life insurance?
What is the difference between the guaranteed column and the projected column?
What happens if I stop paying the premiums?
Why do two people pay different premiums for the same coverage?
Should I disclose a health condition on my application?
Which riders are worth having?
What should I check on the life insurance I already own?
What is Assuris, and does it protect my policy?
Can I have both term and permanent coverage at the same time?
How long before a whole life policy has meaningful cash value?
Can I borrow against whole life insurance?
Is whole life insurance worth it?
Sources
- Income Tax Regulations, Regulation 306, Justice Laws Canada, verified 2026-08-21
- Income Tax Act s.12.2, s.148 and subsection 89(1), Justice Laws Canada, verified 2026-09-24
- Assuris, Whole Life protection, net of policy loans, verified 2026-09-23
About the author

Jose Salloum is a Financial Security Advisor (conseiller en sécurité financière) certified by the Autorité des marchés financiers in Quebec, a Life and Accident & Sickness Insurance Agent licensed by the Financial Services Regulatory Authority of Ontario, and a Life Insurance Agent licensed by the Insurance Council of British Columbia. Licensed since 2001.
He has practised Infinite Banking since 2015 and founded Canadian Wealth Creation Centre Inc. in 2016. From 2020 to 2024 he was an IBC (Infinite Banking Concepts™) Authorized Practitioner of the Nelson Nash Institute, a private certification rather than a regulatory licence.
IBC Financial is the educational website of Canadian Wealth Creation Centre Inc., open to all Canadians. Services come only from Canadian Wealth Creation Centre Inc. Its representatives hold a licence in each province served: Quebec, Ontario, Alberta, British Columbia, Manitoba and New Brunswick. Jose Salloum's own licences cover Quebec, Ontario and British Columbia. This page is general education and not advice on any individual file.
Last reviewed 2026-09-24. By Jose Salloum, Financial Security Advisor in Quebec. In Ontario, Life and Accident & Sickness Insurance Agent. In British Columbia, Life Insurance Agent.